If you’re a first-time homebuyer on Anna Maria Island, flood insurance is the cost that catches most buyers off guard. Listing prices and mortgage estimates look manageable until flood insurance enters the conversation and changes the math.
Understanding these premiums is essential to making a smart financial decision, whether you are buying, investing, or already own here. The island sits in a coastal flood zone, so your property will carry some risk no matter where it sits.
FEMA’s Risk Rating 2.0 system has reshaped how premiums are calculated across the Gulf Coast, and the results vary from property to property. This guide breaks down what flood insurance actually costs on Anna Maria Island in 2026, zone by zone. Some properties pay under $2,000 a year, while others face bills above $15,000, depending on elevation and construction.
Anna Maria Island Real Estate Market Snapshot
The Anna Maria Island real estate market continues to attract strong interest heading into 2026. Median home prices in the Manatee County coastal zone hover around $850,000 to $1.1 million for single-family homes. Waterfront and Gulf-front properties regularly list well above $1.5 million.
Inventory is tight, with fewer than three months of supply for desirable properties. Demand from out-of-state buyers, particularly from the Northeast and Midwest, stays consistent year-round.
Vacation rental performance on the island is solid despite broader economic uncertainty. Peak season occupancy rates run between 80 and 95 percent for well-managed properties. Weekly rental rates for Gulf-view homes range from $3,500 to $8,000 depending on season and location.
Investors still see Anna Maria Island as a premium short-term rental market. However, carrying costs like flood insurance now play a larger role in calculating return on investment.
How Risk Rating 2.0 Changed the Game for Island Properties
FEMA launched Risk Rating 2.0 in October 2021, and its effects are now clear. The old system grouped properties into broad flood zones with uniform pricing. Risk Rating 2.0 evaluates each property individually based on multiple factors. These include distance to water, elevation, building type, replacement cost, and historical flood frequency.
For Anna Maria Island, this shift has produced a wide range of outcomes. Some elevated newer construction homes saw premiums stay flat or even decrease slightly. Older ground-level properties near the Gulf or bay experienced significant premium increases.
The system is designed to be more equitable, but it creates winners and losers on the same street. A property that qualified for a low premium five years ago might rate very differently today.
Risk Rating 2.0 caps annual premium increases at 18 percent per year for existing policyholders. That cap softens the blow, but you could still face several years of increases in a row. A property rated at $5,000 annually today could climb to nearly $8,500 within four years.
Flood Insurance Premiums by Zone and Property Type
Flood insurance premiums through the National Flood Insurance Program vary considerably across Anna Maria Island in 2026. A newer elevated home in an AE flood zone might pay between $1,800 and $3,500 annually. An older slab-on-grade home closer to the water could face premiums from $5,000 to $12,000 per year.
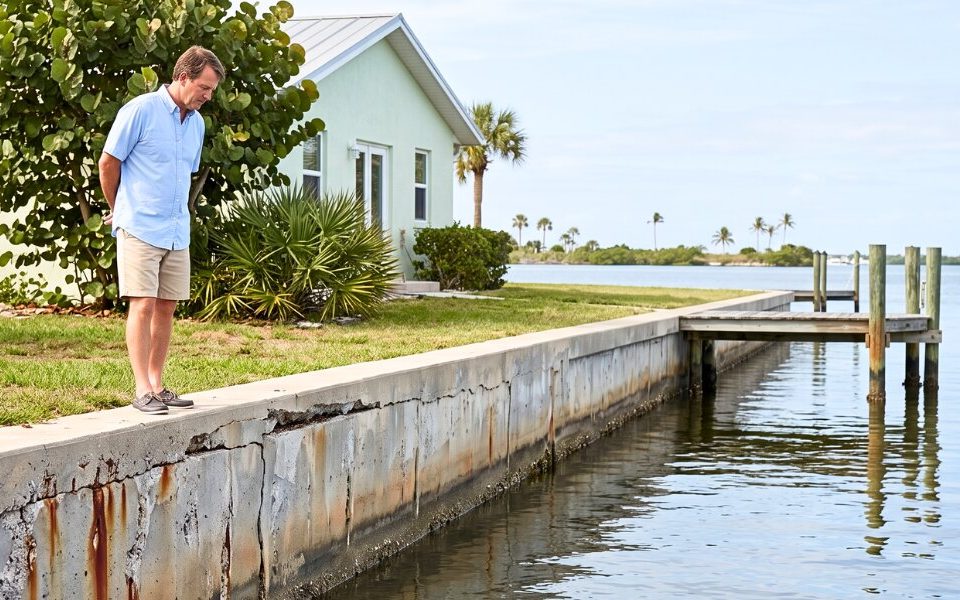
Properties in the VE zone, which covers the most storm-surge-prone coastal areas, see the highest costs. Premiums for ground-level structures in VE zones can reach $15,000 or more annually. Gulf-front homes with older construction and lower elevation certificates often fall into this category. These numbers can surprise you if you only looked at purchase price and property taxes.
The private flood insurance market offers alternatives worth exploring. Several private carriers write policies in coastal Florida, and you could save 20 to 40 percent with the right one. Private policies vary widely in coverage terms and claims handling, so compare deductibles, coverage limits, and exclusions before switching from an NFIP policy.
Strategies for Managing Flood Insurance Costs
Elevation is the most impactful factor in reducing flood insurance premiums. Homes built or retrofitted to meet current FEMA elevation standards pay dramatically less. Raising a home can cost $100,000 or more, but the long-term insurance savings often justify the investment. An elevation certificate is essential, since it documents your property’s height relative to the base flood elevation.
Request the seller’s current flood insurance declaration page during your due diligence period. This document shows the exact premium, coverage amounts, and policy details. Do not rely only on estimates from online calculators for this figure. Ask your insurance agent to run a quote specific to the property using its elevation certificate and address.
If you plan to rent the property to vacationers, factor flood insurance as a deductible expense in your rental income projections. A property generating $60,000 in gross rental revenue looks different once $8,000 goes to flood insurance alone. Building these costs into your numbers from day one keeps your return-on-investment math honest. A local agent can pull comparable flood insurance quotes before you ever make an offer.
FAQs About Flood Insurance on Anna Maria Island
Is flood insurance required on Anna Maria Island?
Yes, if you have a federally backed mortgage on a property in a high-risk flood zone. Most of Anna Maria Island falls within FEMA-designated AE or VE zones. Even without a mortgage requirement, you should consider carrying flood insurance given the island’s coastal exposure.
Can I get flood insurance through a private company instead of NFIP?
You can, since several private insurers offer flood policies in coastal Florida markets. Private policies sometimes offer better rates or higher coverage limits, so compare at least three quotes and review terms before committing.
How does elevation affect my flood insurance premium on Anna Maria Island?
Elevation is the most significant factor in determining your premium under Risk Rating 2.0. A home elevated several feet above base flood elevation can save thousands annually. Getting an elevation certificate is the first step in understanding your property’s rating.
Do flood insurance costs differ between Anna Maria, Holmes Beach, and Bradenton Beach?
Premiums vary by property, not by city boundaries. However, properties closer to the Gulf in any of these three communities carry higher risk ratings. Elevation, construction type, and distance to water matter more than your mailing address.
Talk Through the Real Costs of Island Ownership With Billi
Ready to buy on Anna Maria Island while accounting for flood insurance? Reach out to Billi for a carrying-cost analysis on any property you have your eye on. She can walk you through zone-specific numbers before you make an offer, not after.